Business vehicle finance · ABN holders only
Finance the vehicle your business runs on.
From a single second-hand ute to a full fleet — chattel mortgages, hire purchase, leases and sale and leaseback explained in plain English, with one specialist on your side.
- No credit check to enquire
- Dealer, private or auction
- New, demo or used
Quick check · 3 questions
Which structure usually fits?
Usually fits
Chattel mortgage
Your business owns the vehicle from day one, and the GST in a dealer's price is usually claimable for business use.
How it works →How we work
Three promises, kept on every enquiry
No credit check to enquire
Asking what's possible for your next vehicle leaves your credit file untouched. A credit check only comes up once you decide to apply.
Not spread around
Your details aren't fired off to a crowd of lenders. One specialist works out which structure and lender suit the vehicle and your business.
A real person on it
Someone who knows vehicle finance reads your enquiry and calls you. Accurate answers on the form let us line up the right option first time.
The structures
Four ways to finance a work vehicle — explained plainly
Who owns the vehicle, when you claim the GST, and what happens at the end. That's most of what separates them.
Chattel mortgage
Your business owns the vehicle from day one; the lender holds security over it. The everyday choice for GST-registered buyers.
- Owner
- You
- GST
- On purchase
- End
- Nothing owing
Commercial hire purchase
The financier owns it until your last payment, then it's yours. Some accountants prefer it for reporting.
- Owner
- Financier, then you
- GST
- Up front (since 2012)
- End
- Title passes
Finance lease
Lease the vehicle with an agreed residual. GST sits in each payment, which some businesses prefer for cash flow.
- Owner
- Financier
- GST
- Each payment
- End
- Pay, refinance or sell
Sale and leaseback
Sell vehicles you already own to a financier and lease them straight back — cash released, keys kept.
- Owner
- Financier
- GST
- Each payment
- End
- As per lease
Also explained: operating leases · novated leases for employers · refinancing · balloons · low-doc · property-backed fleets
Free tool
The business vehicle finance planner
Choose the vehicle, the seller, the price band, your ABN age, GST status, business use and whether you own property. See the structures that usually fit, what each means for GST and ownership, a documents checklist and your next steps — no rates, nothing sent anywhere.
- Ranked structures for your situation
- GST and ownership in one line each
- Car limit, LCT and write-off flags
- A documents list you can print
- Realistic next steps
How it works
From enquiry to keys in four steps
- 1
Tell us about the vehicle
A 60-second enquiry: the vehicle, the seller, your ABN and how it'll be used. No credit check at this point.
- 2
A specialist calls you
One person who knows vehicle finance works through your situation and the structures that fit.
- 3
Approval as fast as possible
We gather only the documents your lender needs and push for approval without delay.
- 4
Settle and drive
The lender pays the dealer, seller or auction house directly. You collect the keys.
Myth-buster
Five things owners get wrong about vehicle finance
Most of the expensive mistakes we hear about come from a half-remembered rule. Here are the usual suspects.

“I'll write the whole ute off at tax time.”
The ATO's instant asset write-off is for assets costing less than $20,000 each, for eligible businesses. Most new utes cost more, so they're depreciated instead. Find out more
“A private sale is always cheaper.”
Private sellers usually don't charge GST, so there's no credit to claim. Compare a dealer price after the GST credit you'd get back. Find out more
“I can claim all the GST on any car.”
Passenger cars are capped at one-eleventh of the car limit — $6,353 for 2026–27. Many goods utes and vans aren't capped. Find out more
“A new ABN can't get vehicle finance.”
New ABNs are considered case by case. Experience, work lined up, a deposit or property ownership all help. Find out more
“A bigger balloon is free money.”
A balloon lowers repayments but raises the total cost and leaves a lump sum at the end. Plan the exit first. Find out more
Tax and costs
The numbers that matter, checked against the ATO
Figures from ato.gov.au, checked October 2026. Your accountant confirms how they apply to you.
Who we help
Vehicle finance by industry
The vehicle questions tradies, couriers, farmers and mobile businesses actually ask.
Tradies
Vehicle finance for electricians, plumbers, builders and other tradies: utes, vans, trailers, fit-outs, new ABNs, GST credits and keeping cash for jobs.
See more →Couriers and last-mile
Van and vehicle finance for owner-driver couriers and last-mile delivery businesses: contracts, platform income, high kilometres, EV vans and growing a fleet.
See more →Rideshare and taxi
Car finance for rideshare and taxi drivers with an ABN: GST registration, platform earnings, vehicle rules, hybrids and EVs, logbooks and the car limit.
See more →Farmers
Vehicle finance for farmers and primary producers: farm utes, trucks, livestock trailers and 4WDs, seasonal repayment options and planning around harvest.
See more →Construction
Vehicle finance for builders, civil contractors and subcontractors: crew utes, tippers, plant trailers and service trucks, funded around progress payments.
See more →Food trucks
Financing a food truck, coffee van or catering trailer: itemised fit-outs, council permits, new operators, buying used and choosing truck, van or trailer.
See more →Mobile services
Van and vehicle finance for mobile mechanics, dog groomers, car detailers, cleaners, locksmiths and other businesses that take the service to the customer.
See more →Removalists
Finance for removalists: pantechs, large vans and tail-lifts, licence classes, seasonal peaks and growing from one truck to a small fleet.
See more →Guides
Before you buy your next vehicle
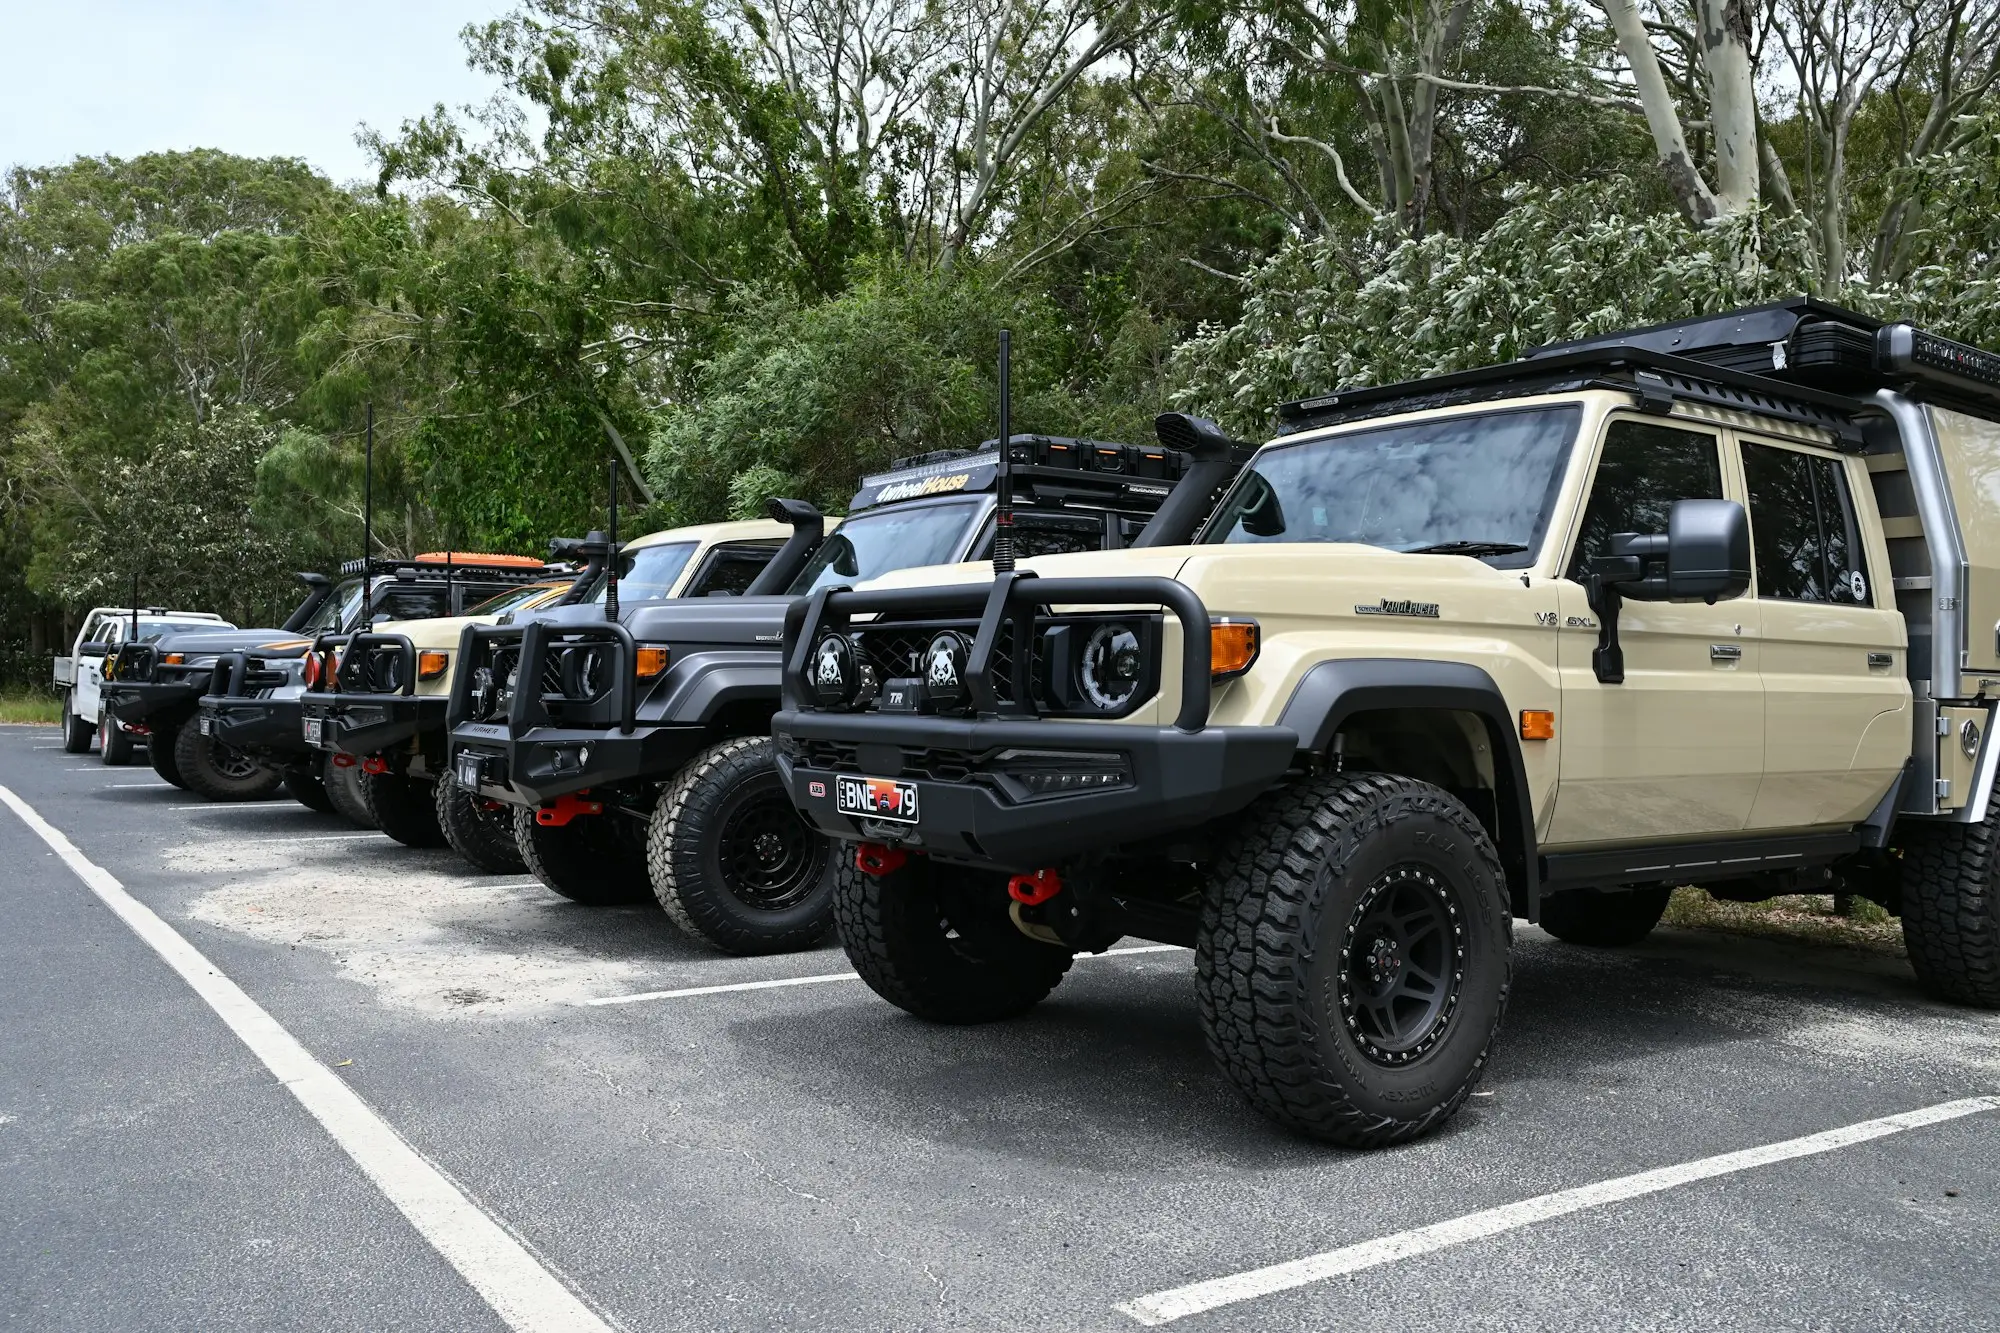
Buying a Work Vehicle Before 30 June: What Counts
Buying a ute, van or truck before EOFY? What 'first used or installed ready for use' means, the $20,000 write-off test, the car limit and finance timing.
Business Vehicle Finance Documents: The Full Checklist
Exactly what to gather before applying for business vehicle finance — ID, ABN, vehicle details, bank statements, BAS or financials — for every situation.

Repair or Replace Your Work Vehicle? A Decision Guide
Repair bills climbing on your ute, van or truck? How to weigh repair costs, downtime, reliability and finance before deciding to keep it or replace it.
Common questions
What does CarsOne finance?
Business vehicles for Australian ABN holders — cars, utes, vans, 4WDs, light and heavy trucks, prime movers, trailers, buses, EVs and hybrids, prestige vehicles used for business, and whole fleets. Business purposes only; we don't arrange personal car loans.
Does enquiring affect my credit score?
No. There's no credit check when you first enquire. A credit check only happens once you decide to go ahead with an application, and we'll tell you before it does.
Will my details be sent to lots of lenders?
No. One CarsOne specialist works out which structure and lender suit your vehicle and business. We don't spray your details around in the hope that someone bites.
Do you publish interest rates?
No. Every business vehicle deal is priced on its circumstances — the vehicle, your business and the structure — so a headline rate would mislead you. We'll explain the real options on a call.
Can I finance a vehicle from a private seller or an auction?
Yes. Private and auction purchases are usually financed through a chattel mortgage. The lender pays the seller or auction house directly, and for private sales a clean PPSR search is needed.
What if I've had credit problems or have an ATO debt?
Past credit issues and ATO debt are considered case by case. Being upfront on the enquiry form helps us find a lender who'll genuinely consider your situation.
Can property help with a bigger fleet?
Yes. Property-secured business loans from $20,000 to $5,000,000 (first mortgage, second mortgage or caveat) — an option for bigger fleets.
Ready to line up finance for your next work vehicle?
A 60-second enquiry, no credit check when you first enquire, and a vehicle-finance specialist who calls you back with the structure that suits.
No credit check to enquire
Not spread around
A real person on it